Form 8948 - Preparer Explanation for Not filing Electronically
Online · Written guide Content date 1 min read
On this page
In general, a tax return preparer or tax preparation firm must electronically file tax returns for individuals, estates, and trusts if they reasonably expect to prepare and file more than 11 returns in a calendar year. There are exceptions to this electronic filing requirement, and Form 8948 is used to explain which exception applies for a tax return that has been prepared and filed on paper.
Exceptions to electronically filing a tax return
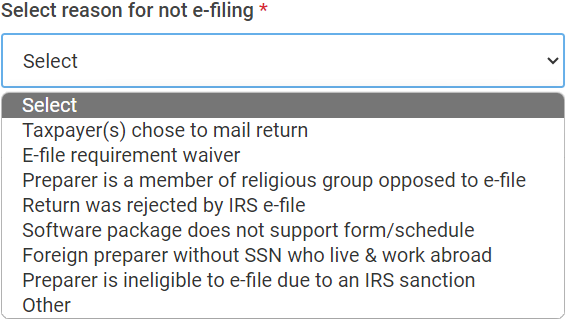
- The taxpayer has chosen to file on paper;
- The tax preparer has received an undue hardship waiver from the IRS for the calendar year in which the return is being filed;
- The tax preparer is a member of a recognized religious group that is opposed to filing electronically;
- The taxpayer attempted to e-file the return but was unable to do so because the return was rejected and the reject condition could not be resolved;
- The tax preparer attempted to e-file the return but the software package used did not support one or more of the forms or schedules that are part of the return;
- The tax preparer is a foreign person without an SSN who cannot enroll in e-file and the tax preparer is not a member of a firm that is eligible to e-file. (This exception assumes the tax preparer has applied for a PTIN and submitted Form 8946, PTIN Supplemental Application For Foreign Persons Without a Social Security Number.);
- Ineligibility due to an IRS sanction;
- Verifiable and documented technological difficulties.
Completing Form 8948
To complete Form 8948 in Tax Processors Plus Online, from the Federal Section of the tax return (Form 1040) select:
- Miscellaneous Forms
-
Preparer Explanation for Not Filing Electronically - Choose the reason in the dropdown menu.:
Additional Information: